The trade licence is issued, the shareholders are ready to trade, and the bank has asked for more documents, or more explanation, than you expected. Under the federal anti-money laundering law's definition of customer due diligence, a UAE bank has to establish who the company is, who ultimately owns or controls it, what the business does and why it needs the account.
The short answer to how you open the account: apply to the bank with a file that lets it complete those checks, and use the rights the CBUAE's new SME Customer Protection Regulation gives SME customers, if your company falls within its definition. That regulation took effect on 13 September 2026. It requires banks to disclose their minimum document requirements, to explain certain delays and, with exceptions, to give written reasons for a rejection.
The current rules list a tax registration number among the company details a bank obtains, so for the tax side start with the overview of UAE corporate tax. This article covers the banking rules as read on 20 September 2026 and a file you can build before your first appointment.
The rules that apply, as read on 20 September 2026
| Instrument | Status shown on the official page | What it governs for your application |
|---|---|---|
| Federal Decree by Law No. (10) of 2025 (anti-money laundering) | UAE Legislation portal: Issue Date 30 September 2025, Effective Date 14 October 2025, Status: Active | The bank's duty to carry out customer due diligence |
| Cabinet Resolution No. (134) of 2025, its Executive Regulations | UAE Legislation portal: Issue Date 29 October 2025, Effective Date 14 December 2025, Status: Active | What the bank must identify and verify |
| Cabinet Resolution No. (109) of 2023, "Regulating the Real Beneficiary Procedures" | UAE Legislation portal: Effective 16 November 2023, Status: Active | Your company's beneficial owner register |
| CBUAE SME Customer Protection Regulation, reference "C 2/2026" | CBUAE Rulebook: "Effective from 13/9/2026" | Your rights as an SME applicant |
Check the date of any older guidance. Article 41 of the 2025 law states: "Federal Decree by Law No. (20) of 2018, referred to herein above, shall hereby be repealed." Article 22 of Cabinet Resolution No. (109) of 2023 states: "The Cabinet Resolution No. (58) of 2020 regulating Real Beneficiary Procedures shall be cancelled."
Two CBUAE pages still carry older references. Its anti-money laundering page, updated on 9 September 2026, names the 2025 law but still says Cabinet Decision No. (58) of 2020 "aims to enhance the transparency of entities registered in the UAE". Its 2021 guidance on serving legal persons, shown "In-Force" in the Rulebook, cites the repealed 2018 law. Where they differ from the current texts, confirm the position with the CBUAE or your bank.
What the law requires a bank to establish
Federal Decree-Law No. (10) of 2025 defines customer due diligence (CDD) in Article 1. It covers "identifying and verifying the information of a Customer or Beneficial Owner, whether a natural or legal person or a legal arrangement". It continues: "as well as identifying the nature of their business, the purpose of the business relationship, and the ownership structure and control thereover, including ongoing monitoring procedures".
Article 19 requires financial institutions to "Implement Customer Due Diligence (CDD) Measures and continuous monitoring procedures, determining their scope based on the multiple risk dimensions". The article continues: "and with due regard to the outcomes of the national risk assessment". Ask your bank how it will scope the checks for your company.
Cabinet Resolution No. (134) of 2025, Article 14(1), sets out what happens where due diligence cannot be applied. Institutions "shall be prohibited from establishing or continuing a Business Relationship or executing a Transaction where they are unable to apply Customer Due Diligence measures".
The company itself
Article 9(1) of Cabinet Resolution No. (134) of 2025 requires institutions to "identify the Customer" and to "verify such identity using original documents, data, or information obtained from a reliable and independent source". For a company, Article 9(1)(b) lists this "basic information":
- "Name, legal form, memorandum of association, tax registration number of the Legal Persons subject to corporate tax, and the unique reference number, if any"
- "Address of the registered office or principal place of business ..."
- "Articles of association or any other equivalent approved documents"
- "Names of relevant persons holding Senior Management positions ..."
The tax registration number appears only for legal persons "subject to corporate tax". Whether and when your company registers is a tax question; see the corporate tax registration steps and confirm your position with the Federal Tax Authority or a licensed tax adviser.
Before you apply, check how to verify a UAE trade licence and make sure the public record matches the documents in your file.
The people who own or control it
Article 10(1)(a) of the resolution sets the ownership test for a company's beneficial owner. The bank identifies "the natural person who ultimately owns, whether individually or jointly with another person, an actual controlling ownership interest or shares in the Legal Person of 25% (twenty-five percent) or more".
Article 10(1) then sets two further tests. Article 10(1)(b) applies, among other cases, "where no natural person exercises control through ownership interest". It looks to "the natural person who exercises legal or actual control over the Legal Person, or through any other means, whether directly or indirectly". Article 10(1)(c) applies "Where no natural person is identified pursuant to paragraphs (a) and (b)". It looks to "the relevant natural person holding a Senior Management position".
What the business does and why it needs the account
Article 9(3) of the resolution states that institutions "shall understand the purpose and the intended nature of the Business Relationship and obtain information relating thereto where necessary". The CBUAE's 2021 guidance on legal persons gives an example: a taxi company "is likely to see substantial cash inflows and make regular, predictable transfers to cover payroll and to a limited set of suppliers". Prepare the equivalent picture for your own company: who pays you, whom you pay, in which currencies and roughly how much.
When source of funds and wealth come in
In the text of Cabinet Resolution No. (134) of 2025 reviewed on 20 September 2026, source of funds appears in two places. Article 5(2)(c), on enhanced due diligence, lists "Taking Reasonable Measures to identify the source of funds and wealth of the Customer and the Beneficial Owner". Article 16(1)(a)(3), on politically exposed persons (PEPs), lists "Taking Reasonable Measures to identify the source of funds and wealth of Customers and Beneficial Owners identified as Politically Exposed Persons".
We did not find source of funds listed as a standard item for all customers in the resolution text, or in Articles 1 and 19 of the 2025 law, as reviewed on 20 September 2026. The bank decides whether enhanced measures apply to your company.
Your company's own beneficial owner records
Separately, Cabinet Resolution No. (109) of 2023 places duties on legal persons licensed or registered in the State. Article 3(2) excludes, among others, "Financial Free Zones"; companies there should confirm which beneficial owner rules apply. Article 5(1) states: "Real Beneficiary of Legal Person is whoever owns or finally controls Legal Person, through direct or indirect ownership shares of (25) twenty-five per cent or more of Legal Person capital."
Article 8(1) requires the company to keep a Real Beneficiary Register "within (60) sixty days from the date of the implementation of this Resolution or from the date of the existence of this Legal Person". Article 11(1) requires it to "submit the data of Real Beneficiary Register and Partners or Shareholders Register to Registrar".
Both texts use a 25 per cent line. Prepare one ownership chart and check it against each text. Where it applies, keep the register current so the names you give the bank match it.
What the SME Customer Protection Regulation adds
The CBUAE Rulebook lists this regulation, reference "C 2/2026", as "Effective from 13/9/2026". Its definitions cover "a Small to Medium Sized Enterprise, including sole proprietors, that obtains or may prospectively obtain Financial Services and/or Products". An SME is defined by reference to "thresholds of employee headcount and turnover", so check with your bank whether your company falls within it. Its account opening rules are quoted below from the Rulebook as read on 20 September 2026.
| Article | What it says | What it means for your preparation |
|---|---|---|
| 4.49 | "Financial Institutions must have clear, transparent and consistent disclosure regarding the minimum documentary requirements for the opening of a Customer Bank Account and ongoing due diligence." | Ask for the bank's published minimum list before you assemble the file |
| 4.46 | Systems "to ensure that the opening of a Customer Bank Account is completed within three (3) business days", subject to the condition quoted below | The three days apply only to the low-risk, standard documentation case |
| 4.48 | Where an accepted application is delayed for "valid circumstances other than Financial Crime Compliance requirements", the bank "must explain the delay to the Customer and document the reason" | Ask for the reason for a delay after acceptance |
| 3.12 | On rejection, the bank "must disclose the reason for rejection in Writing to the applicant", subject to the exception quoted below | A written reason is not available in all cases |
| 3.4(a)(6) | Banks "inform the Customer in a timely manner about the final decision on the application" | No number of days is stated |
| 4.51 | Opening funds "must be blocked until the requirements for opening Bank Accounts are fulfilled, including those relating to Financial Crime Compliance" | Do not plan to use an opening deposit until the account is fully open |
The condition in Article 4.46 reads: "in instances where the Financial Institution has assessed the profile of the applicant to present low money laundering and terrorist financing risks". It continues: "and can demonstrate that it is satisfied with standard Customer due diligence documentation." The period is therefore not a general deadline for all applications.
The exception in Article 3.12 reads: "except where the reason for rejection is related to Financial Crime risks or as may be prohibited by applicable laws and regulations." A bank that declines for a financial crime reason is not required by that article to tell you why.
Article 4.50 adds that opening an account "does not constitute the requirement to permit any type of transaction until the Financial Institution has undertaken all appropriate due diligence". An open account may come with limits until due diligence is complete.
Article 4.31 requires banks to act fairly when considering an account opening, "regardless of their size, income/profits, business growth, Market standing, nationality of the ownership, years of presence and type of business activities". That is qualified by the bank's "risk appetite", and Article 4.47 adds "the risk-based approach" of the 2025 law.
A note on the Rulebook listing. Article 10.1 of C 2/2026 states that the earlier SME Market Conduct Regulation "(Circular No. 1/2021, dated 26/01/2021) is hereby cancelled." On 20 September 2026 the Rulebook still showed the older regulation's pages as "In-Force", with "Effective Date: 26/2/2021". Its parent page said it "will be cancelled and replaced by" the new regulation on 13 September 2026. If a bank cites the older regulation, ask it to confirm the current position with the CBUAE.
Mainland, free zone and address questions
We did not find an official statement setting different bank account documents for mainland and free zone companies on the pages reviewed on 20 September 2026: the CBUAE Rulebook pages cited here, the text of Cabinet Resolution No. (134) of 2025 and the UAE Government Portal's banking page. For setup differences, see the mainland or free zone decision, mainland company setup in Dubai and free zone company setup in Dubai.
We also did not find an official requirement to hold a tenancy contract to open a company account on those pages. The resolution asks for the "Address of the registered office or principal place of business". Ask your bank which address evidence it accepts. If you are weighing a shared office, see the explainer on business centres in Dubai.
If the company is not yet formed, start with the overview of business setup in Dubai.
Build the file before the appointment
The asset follows the legal requirements. [Law] marks words quoted from the legal text. [Prepare] marks our suggested practice, not a legal requirement. [Bank list] marks an item that ADCB's own FAQ for its business account lists: one bank's list, not a legal rule, so ask your bank for its published minimum list.
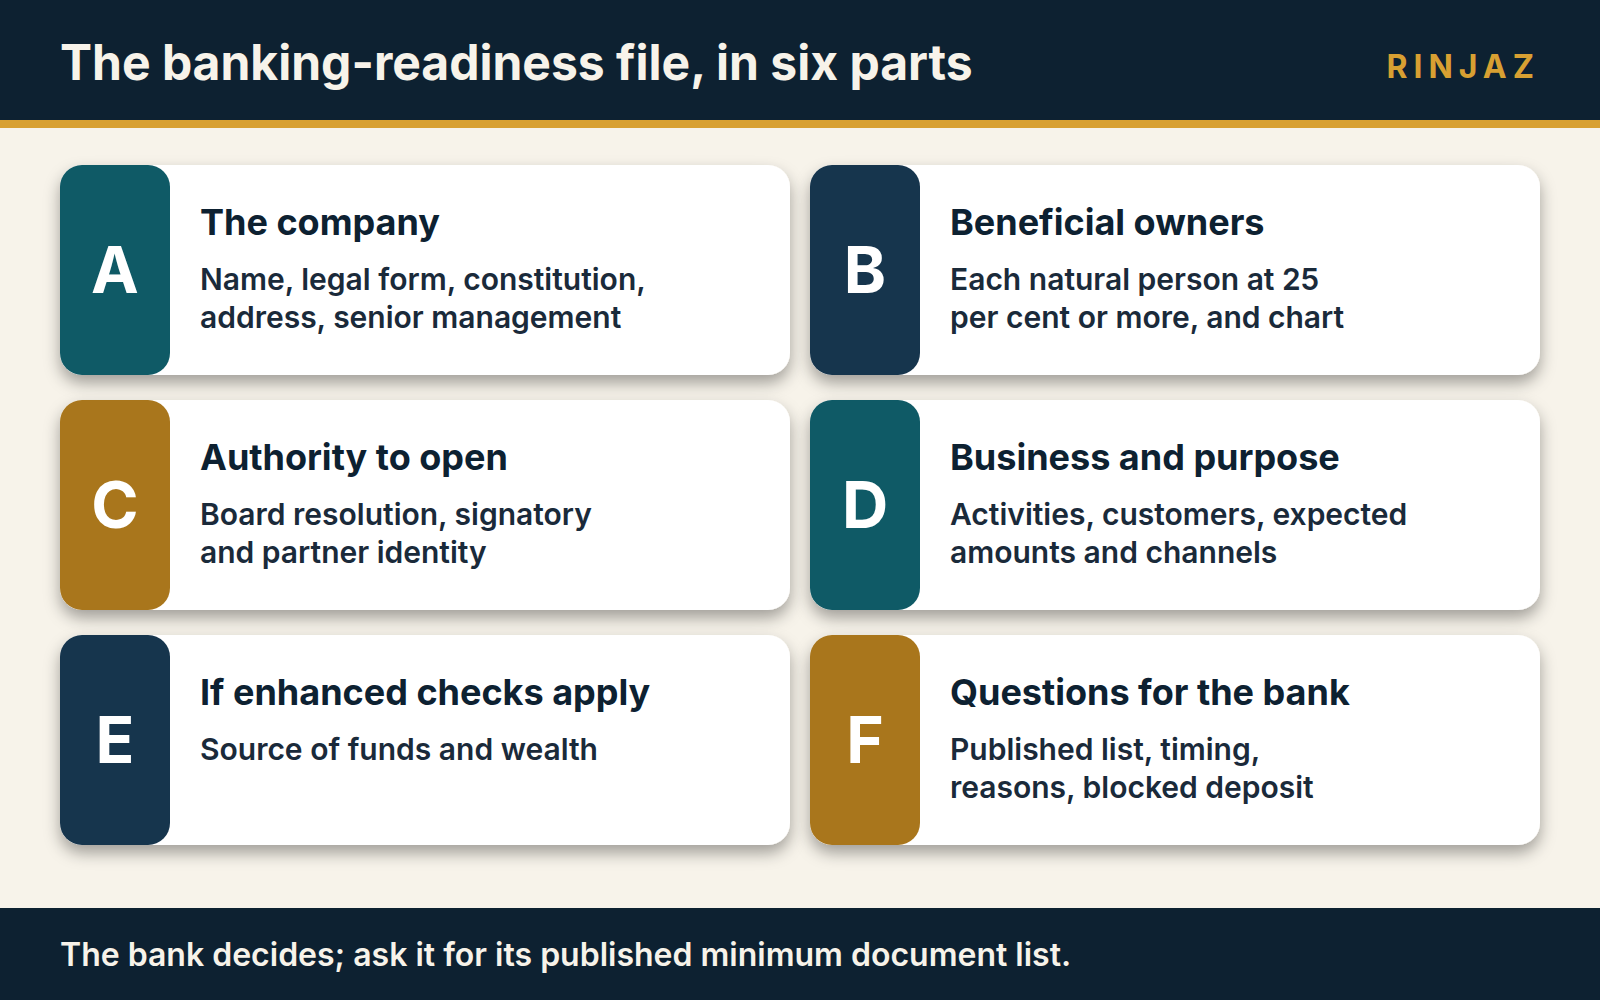
Practical asset: the banking-readiness file. Tick each line when the document is in the file, and note where the original is held. Part A. The company (Cabinet Resolution No. (134) of 2025, Article 9) 1. [Law] "Name, legal form". [Bank list] "Trade License and commercial registration (as applicable)". 2. [Law] "memorandum of association"; "Articles of association or any other equivalent approved documents". 3. [Law] "tax registration number of the Legal Persons subject to corporate tax, and the unique reference number, if any". 4. [Law] "Address of the registered office or principal place of business ...". [Bank list] "Company address proof". 5. [Law] "Names of relevant persons holding Senior Management positions ...". [Prepare] Ask your bank whether it also needs their identity documents. Part B. Beneficial owners (Article 10; Cabinet Resolution No. (109) of 2023) 6. [Law] "an actual controlling ownership interest or shares in the Legal Person of 25% (twenty-five percent) or more" (Article 10(1)(a)). [Prepare] The identity of each natural person at that level, including anyone holding through another company. 7. [Prepare] A copy of the Real Beneficiary Register and the partners or shareholders register that the company keeps and submits to its Registrar, where Cabinet Resolution No. (109) of 2023 applies to it. 8. [Prepare] An ownership chart that runs from the company to each natural person, with percentages, and the constitutional documents of any company in the chain. Part C. Authority to open the account 9. [Bank list] "Board Resolution authorizing the account opening", and "Power of Attorney (if applicable)". 10. [Bank list] Passport or Emirates Identity of the "authorized signatory and partners (if applicable), including ultimate beneficial owners". Part D. Nature of the business and purpose of the account (Decree-Law No. (10) of 2025, Article 1; Resolution Article 9(3)) 11. [Prepare] A one-page description of the business: licensed activities, main customers and suppliers, countries involved. 12. [Prepare] Expected monthly incoming and outgoing amounts, currencies and channels, including cash. Part E. If the bank applies enhanced due diligence or measures for politically exposed persons (Articles 5(2)(c) and 16(1)(a)(3)) 13. [Law] "identify the source of funds and wealth of the Customer and the Beneficial Owner" (Article 5(2)(c)). [Prepare] Material explaining it, if the bank requests it. Part F. Questions to ask the bank (CBUAE SME Customer Protection Regulation, C 2/2026) 14. [Prepare] Where is your published list of minimum documents for opening and for ongoing due diligence? (Article 4.49) 15. [Prepare] Have you assessed our profile as low risk, and does the three-business-day completion in Article 4.46 apply? 16. [Prepare] If the application is accepted but delayed, what is the reason? (Article 4.48) 17. [Prepare] If the application is rejected, will you give the reason in writing, where Article 3.12 permits it? 18. [Prepare] Is our opening deposit blocked, and until which step? (Article 4.51) 19. [Prepare] Which transactions are available once the account opens, and which wait for further due diligence? (Article 4.50)
A worked example: two founders each hold 50 per cent, one through a holding company abroad. Part B then needs the holding company's documents and a chart showing that founder as the natural person behind it.
The bank, not any provider, decides whether to open your company account, applying the 2025 law, Cabinet Resolution No. (134) of 2025 and the CBUAE regulation. Where Cabinet Resolution No. (109) of 2023 applies, your company keeps its own beneficial owner registers. No provider can change the bank's assessment.
This article describes published requirements and is not legal or financial advice.
Information verified against official sources on 20 September 2026.
If you want help assembling the documents for a corporate account application, contact RINJAZ to confirm availability, scope and quotation. RINJAZ is a privately licensed UAE service provider. It is not a government entity and does not act for any authority.
A provider's role, within whatever its licensed activity covers, is to prepare documents, submit them through the correct channel and track progress. The bank decides whether to open the account, under the federal law and the Central Bank of the UAE's rules, and no provider can promise the outcome.
Clear answers, without the clutter
How long does a UAE bank take to open a company account?
Does a bank have to give a reason for rejecting a company account application?
What company information does a UAE bank have to obtain?
Who counts as a beneficial owner when a company opens a bank account?
Will the bank ask where the company's money comes from?
Can I use money deposited before the account is fully open?
Official sources
Primary government and institutional references used to verify this guide. Open any source in a new tab for the current authority wording.
- uaelegislation.gov.aepage updated 18 Sep 2026↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aepage showed Last Updated 18 September 2026↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aepage updated 6 Nov 2023↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- rulebook.centralbank.aeOfficial guidance and service information↗
- centralbank.aepage updated 9 Sep 2026↗
- UAE Government Portalpage updated 4 Sep 2026↗
- adcb.comOfficial guidance and service information↗