Your sales are growing and a customer has asked for your Tax Registration Number. You need to know whether the business has crossed the line, and how long you have once it does.
The Federal Tax Authority (FTA) publishes two figures and the period over which each is tested. For businesses resident in the UAE, its VAT registration service page (updated 19 August 2026) states that registration is mandatory if "The total value of taxable supplies and imports exceeds AED 375,000 over the past 12 months, or is expected to exceed that threshold within the next 30 days." For resident businesses "that make taxable supplies", the voluntary test reads: "The total value of taxable supplies, imports, or taxable expenses in the past 12 months, or expected in the next 30 days, exceeds AED 187,500." The same page gives the application window as "within 30 days of being required to register". Non-resident businesses are covered below.
Corporate tax is a separate registration, covered in our overview of UAE corporate tax. The Ministry of Finance states: "Value Added Tax (VAT) was introduced across the UAE on 1st January 2018 at a standard rate of 5%."
This article sets out what the official pages say, where they differ, and a monthly worksheet. It does not tell you whether your business must register. The FTA decides registration applications, and a licensed UAE tax adviser can assess your own figures.
RINJAZ is not a licensed tax adviser. This article describes published requirements. Obtain advice from a licensed UAE tax adviser before acting.
The two figures, as each official page publishes them
The five official sources reviewed on 20 September 2026 agree on the amounts; their wording of the period differs.
| Source | Mandatory wording | Voluntary wording | Page date |
|---|---|---|---|
| FTA, VAT registration service page | "exceeds AED 375,000 over the past 12 months, or is expected to exceed that threshold within the next 30 days" | "taxable supplies, imports, or taxable expenses in the past 12 months, or expected in the next 30 days, exceeds AED 187,500" | Updated 19 Aug 2026 |
| FTA, "Registration for VAT" topic page | "The mandatory registration threshold is AED 375,000." | "The voluntary registration threshold is AED 187,500." | Updated 06 Apr 2026 |
| Executive Regulation, Ministry of Finance consolidated text, Articles 7(1) and 8 | "The Mandatory Registration Threshold shall be AED 375,000 (three hundred and seventy-five thousand dirhams)." | "The Voluntary Registration Threshold shall be AED 187,500 (one hundred and eighty-seven thousand five hundred dirhams)." | Amendments shown to Cabinet Decision No. 100 of 2024 |
| Ministry of Finance, VAT page | "the mandatory registration threshold of AED 375,000" | "the voluntary registration threshold of AED 187,500" | Footer 17/09/2026 |
| UAE Government Portal (u.ae), VAT page | "exceed AED 375,000 per annum" | "exceed AED 187,500 per annum" | Updated 30 Mar 2026 |
The law, Federal Decree-Law No. (8) of 2017, provides that "The Executive Regulations of this Decree-Law shall determine" the thresholds. The Executive Regulation is Cabinet Resolution No. (52) of 2017, shown as "Active" on the UAE Legislation portal.
The FTA's VAT legislation page (updated 10 September 2026) also lists an "Executive Regulation of Federal Decree Law No 8 of 2017 and its amendments" with an issue date of September 1, 2026. We could not open it on 20 September 2026; confirm the current text with the FTA.
"Over the past 12 months", "in the next 30 days" and "per annum"
On the FTA service page, the "over the past 12 months" test sits under "Businesses resident in the UAE". The FTA's topic page sets out the mandatory test in two limbs. The first reads: "The total value of its taxable supplies and imports exceeds the mandatory registration threshold over the previous 12 months". The second reads: "The business anticipates that the total value of its taxable supplies and imports will exceed the mandatory registration threshold in the next 30 days."
The Decree-Law, Article 13(1), uses the same structure for residents. The first condition reads: "The value of the supplies...exceeds, during the previous (12) twelve-month period, the Mandatory Registration Threshold". The second reads: "It is expected that the value of the supplies...will exceed the Mandatory Registration Threshold during the next (30) thirty days".
The UAE Government Portal states "If the taxable supplies and imports of a UAE-based business exceed AED 375,000 per annum", and the Ministry of Finance VAT page gives no period. We do not resolve that difference. Ask the FTA which period your figures should be tested against.
The worksheet below follows the FTA's "past 12 months" and "next 30 days" wording so that you can show an adviser both limbs; it does not settle which wording applies.
We did not capture an official statement of which supplies are left out of the threshold calculation from the Executive Regulation and Decree-Law texts reviewed on 20 September 2026. Ask a licensed UAE tax adviser which of your sales and imports belong in the figures.
Voluntary registration and the "taxable expenses" wording
The FTA service page frames its voluntary test for resident businesses "that make taxable supplies". Both FTA pages include "taxable expenses" in the voluntary test (see the table above). The Decree-Law, in Article 17, refers to "The value of supplies...or the taxable expenses incurred during the previous twelve months has exceeded the Voluntary Registration Threshold".
The Ministry of Finance VAT page does not mention expenses: "They may also opt for voluntary registration if their taxable supplies and imports are below the mandatory threshold but exceed the voluntary registration threshold of AED 187,500." The u.ae page states: "VAT is optional for businesses whose supplies and imports exceed AED 187,500 per annum".
Confirm with the FTA which basis it will apply to your application. The Executive Regulation adds, in Article 8: "The Authority shall determine the evidence it may deem necessary to demonstrate eligibility for voluntary Tax Registration."
Whether voluntary registration suits your business is a question for a licensed UAE tax adviser. If you are still setting up to sell online, the licensing side is covered in our guide to the e-commerce trade licence in Dubai.
Businesses based outside the UAE
The FTA service page states, for non-resident businesses: "VAT registration is mandatory if: The business makes taxable supplies in the UAE, even if the value of supplies does not exceed the threshold, unless there is another party in the UAE responsible for settling the VAT on those supplies."
The FTA topic page is shorter: "The mandatory registration threshold is AED 375,000. This threshold is not applicable to foreign businesses." We did not find the "another party" condition on that page as reviewed on 20 September 2026.
Article 13(2) of the Decree-Law applies to "Every Person who does not have a Place of Residence in the State or in one of the Applying States". Such a person "shall register for the Tax if such Person makes supplies of Goods or Services and no other Person obligated to pay the Due Tax for such supplies is in the State."
The u.ae page carries a similar condition. The wording differs across these pages. A foreign business should confirm its position with the FTA or a licensed UAE tax adviser.
We did not find an application deadline stated in days for non-resident businesses in Article 7 of the Executive Regulation as captured on 20 September 2026.
Branches, sole establishments, groups and zero-rated suppliers
Branches. The FTA service page answers the branch question directly: "No. A company with multiple branches is not required to register each branch separately. All branches are registered under a single Tax Registration Number (TRN)." It adds: "A single VAT return must be submitted covering all branches."
Sole establishments owned by one person. The same page states that "All sole establishments owned by the same natural person must be registered under a single Tax Registration Number (TRN)". It continues that "the VAT registration threshold is calculated based on the combined value of the activities of all sole establishments owned by that natural person."
Tax groups. Article 14(1) of the Decree-Law states: "Two or more persons practicing the business may apply for the tax registration as a tax group if the following conditions are satisfied". The first two conditions read: "a. Each of them shall have a business establishment or fixed establishment in the State. b. The relevant persons shall be related parties." We did not capture the remaining conditions of Article 14. Take group questions to a licensed UAE tax adviser.
Zero-rated supplies only. Article 15(1) of the Decree-Law states: "The Authority may exempt the Taxable Person, whether registered or unregistered, from the Tax Registration, upon their request, if their supplies are zero-rated only." We did not find this exception on the FTA service page or topic page reviewed on 20 September 2026. Ask the FTA how to apply for it.
Designated Zones. The FTA service page asks whether businesses "established in a Designated Zone and engaged in the trade of goods" must register. It answers: "This depends on the nature of the activities and supplies carried out by the business and whether it meets the mandatory or voluntary VAT registration requirements in accordance with the VAT legislation." The choice of jurisdiction itself is covered in our mainland or free zone decision guide.
The 30-day clock and the late-registration penalty
The FTA service page states: "The person required to register for VAT must submit a registration application with the FTA within 30 days of being required to register." It continues: "In case of failure to submit the registration application within the specified deadline, a late registration penalty will be imposed".
The Executive Regulation, in the Ministry of Finance consolidated text, Article 7(2), gives the same window: "Person required to register for Tax must file a Tax Registration application with the Authority within 30 (thirty) days".
The penalty amount. We did not find an amount on the FTA service page or topic page reviewed on 20 September 2026. The Ministry of Finance publishes a consolidated text of Cabinet Decision No. 40 of 2017 "and its amendments", headed "This is not an official Translation". Its first page lists amendments up to Cabinet Decision No. 129 of 2025, issued 9 October 2025, shown as "Effective from 14 April 2026".
In that text, Table No. 1, under the column "Administrative Penalty in AED", item 3 reads: "Failure of the Taxable Person to submit a registration application within the timeframe specified in the Tax Law." The penalty shown is "10,000". Confirm the current amount with the FTA before relying on it.
When the clock starts. The date on which your business became "required to register" is a point to confirm with the FTA or your adviser. The worksheet records the month your figures first passed a marker, so that conversation starts with evidence.
Coming off the register is a separate FTA service, whose page states that where deregistration is mandatory the application "must be submitted within 20 business days from the date the deregistration obligation started"; closure more widely is covered in our article on company cancellation and liquidation.
A worked example of the "past 12 months" total
The figures below are invented. They show the arithmetic only, not whether any sale counts as a taxable supply or whether a business must register.
A business records AED 28,000 of sales a month for twelve months. Its total over the past 12 months is AED 336,000 (12 x 28,000). That is below the published AED 375,000 and above AED 187,500.
In month 13 it records AED 45,000. Month 1 drops out, so the new total is AED 353,000 (336,000 minus 28,000 plus 45,000). In month 14 it records AED 52,000. Month 2 drops out, so the total becomes AED 377,000 (353,000 minus 28,000 plus 52,000).
On the arithmetic, the total over the past 12 months has now passed the published AED 375,000 figure. That is the point to take the worksheet and records to a licensed UAE tax adviser or the FTA. How the next-30-days limb is measured is also a question for them.
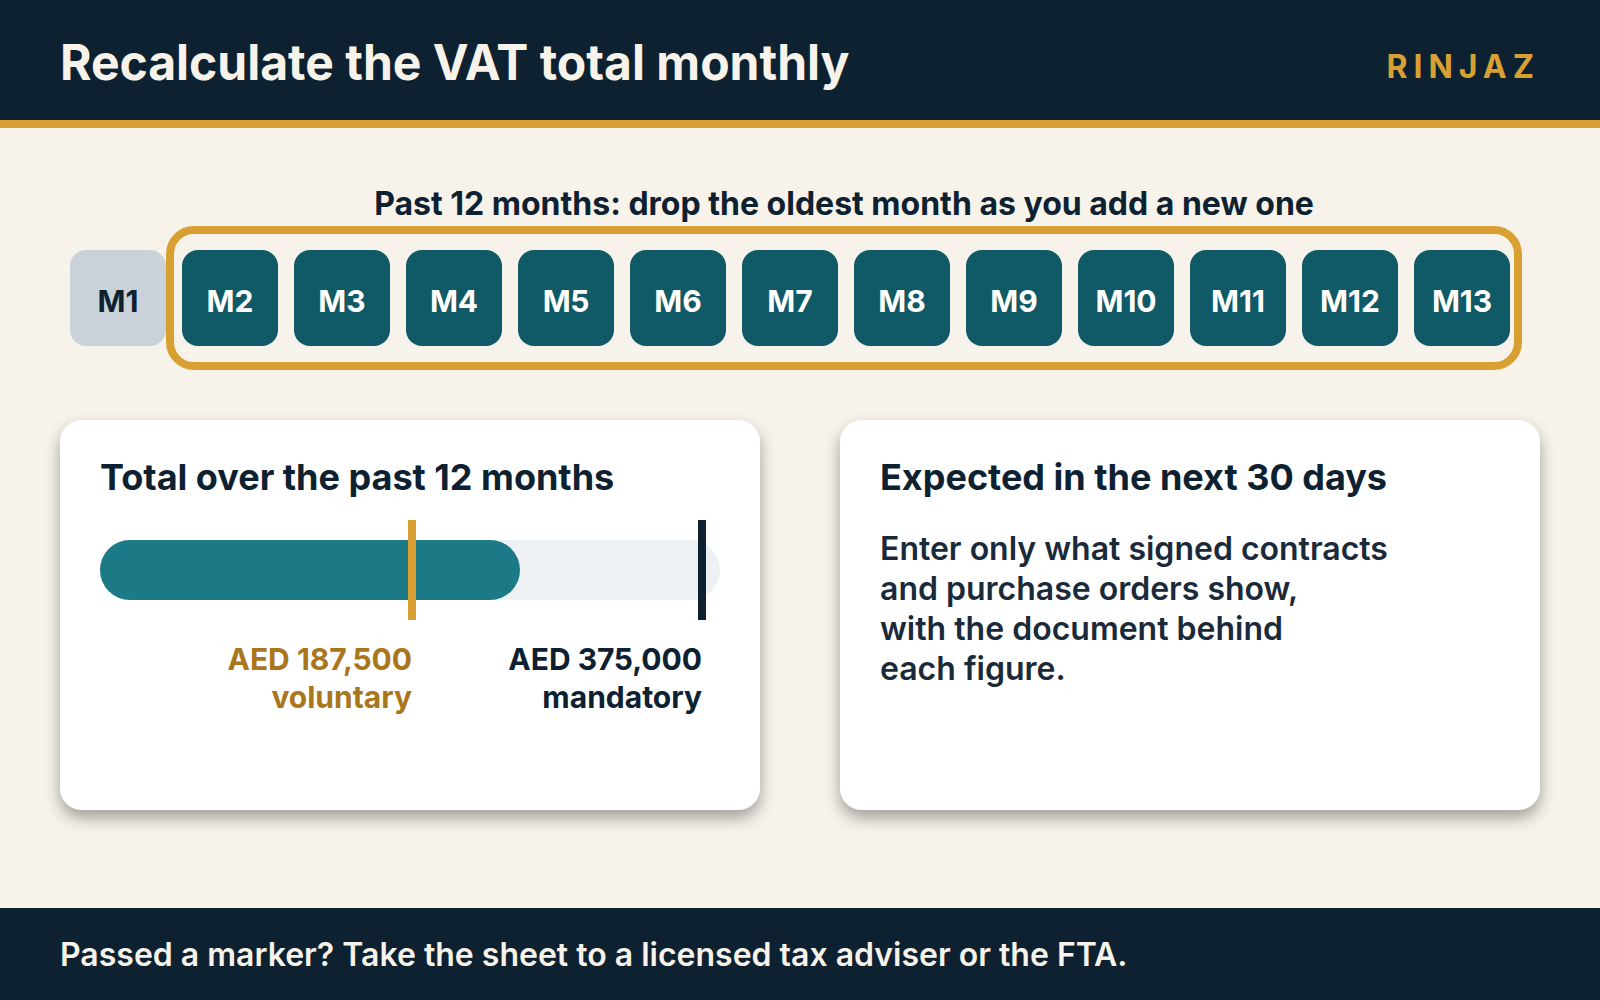
Practical asset: the "past 12 months" VAT threshold worksheet. This is a planning tool, not a tax determination. Keep one sheet per business (one combined sheet for all sole establishments owned by the same person, per the FTA service page) and update it at each month end. | Month | Taxable supplies (AED) | Imports (AED) | Taxable expenses (AED, voluntary wording only) | Previous 12 months total | Next 30 days expected, with documents | Past AED 187,500? | Past AED 375,000? | |---|---|---|---|---|---|---|---| | Month 1 | | | | | | | | | Month 2 | | | | | | | | | Months 3 to 11 | | | | | | | | | Month 12 | | | | | | | | | Month 13 (drop month 1) | | | | | | | | Monthly routine. 1. Enter the month's figures from your accounting records. 2. Add the latest 12 months to get the "Previous 12 months total". Drop the oldest month when you add a new one. 3. In "Next 30 days expected", enter what signed contracts and purchase orders show, and note the document behind each figure. 4. Compare with the published figures: AED 375,000 (mandatory) and AED 187,500 (voluntary), as the FTA service page and the Executive Regulation state them. The expenses column relates to the FTA and Decree-Law voluntary wording only. 5. If a figure passes a marker, note the date and take the sheet to a licensed UAE tax adviser or the FTA. The 30-day clock. The FTA service page states the application must be made "within 30 days of being required to register". Enter the date you are advised the obligation arose: ____. Enter the date 30 days later: ____. Document checklist (items as the FTA service page lists them; tick only when you hold the document). Which items apply to which type of applicant was not captured, so confirm the list on EmaraTax. 1. "Certificate of Incorporation, Memorandum of Association, or Partnership Agreement" 2. "Commercial registration certificate" 3. A "valid trade license" 4. "Emirates ID and passport copies" 5. "Power of attorney document" 6. "Official declaration letter" of taxable supplies and monthly sales 7. "Supporting documents", such as invoices, purchase orders and contracts 8. "VAT invoices" 9. "Expected revenues supported by valid documents" 10. "Bank letter" 11. "Customs information (if applicable)" 12. Registration documents for clubs, charities or associations (where relevant) 13. A copy of the decree (for government entities)
Applying on EmaraTax: steps, fee and time
The FTA lists the channel as "EmaraTax platform: 24 hours a day, 7 days a week".
The steps, as the FTA service page lists them:
- "Signup for an EmaraTax account through the FTA's website"
- "Access the EmaraTax account dashboard"
- "Create New Taxable Person Profile"
- Click on "View" to access the Taxable Person Account
- Click on "Register" under "Value Added Tax"
- "Complete the registration process"
The page states that the application takes "45 Minutes" to complete. It gives processing as "20 business days from the date the completed application was received". On the outcome, it states: "Once the registration application is approved, the VAT registration certificate will be available in the dashboard of the taxpayer's e-Services account."
Before you upload the trade licence, check that its details match what you enter; our guide to verifying a UAE trade licence covers the official lookups. Digital access to government portals is covered in our article on UAE Pass for business.
Corporate tax registration is separate. The FTA's corporate tax FAQ page (updated 22 May 2024) states: "Taxpayers will be required to register for UAE CT (and update their details, if required), even if they are already registered for VAT". See our guide to corporate tax registration.
| Type | Line found | Published by |
|---|---|---|
| Government charge | Fees: "Free" | FTA, VAT registration service page |
| Third-party cost | Tax adviser or accountant: no amounts found on the pages reviewed | Ask each firm for a written quote |
| Provider service fee | None stated in this article | Ask any provider for a written schedule |
Fees checked on 20 September 2026.
What the authority decides, what you prepare, what a provider can do
The authority decides. The FTA decides each VAT registration application. No provider can decide or promise that outcome.
You prepare. The records, worksheet, declaration letter and company documents belong to the business.
A provider can help. Within whatever its licensed activity covers, a provider can gather the listed documents and follow the application.
Information verified against official sources on 20 September 2026.
Contact RINJAZ to confirm availability, scope and quotation for preparing your VAT registration file. RINJAZ is a privately licensed UAE service provider. It is not a government entity and does not act for any authority. A provider's role, within whatever its licensed activity covers, is to prepare documents, submit them through the correct channel and track progress. The Federal Tax Authority decides each VAT registration application, and no provider can promise the outcome.
Clear answers, without the clutter
What is the VAT registration threshold in the UAE?
Is the VAT threshold measured over a calendar year?
How long do I have to apply once I cross the threshold?
What is the penalty for late VAT registration?
What documents are required for VAT registration in the UAE?
Can a new company register for VAT voluntarily?
Official sources
Primary government and institutional references used to verify this guide. Open any source in a new tab for the current authority wording.
- tax.gov.aepage updated 19 Aug 2026↗
- tax.gov.aepage updated 06 Apr 2026↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- mof.gov.aeOfficial guidance and service information↗
- tax.gov.aepage updated 10 Sep 2026↗
- mof.gov.aefooter date 17 Sep 2026↗
- UAE Government Portalpage updated 30 Mar 2026↗
- mof.gov.aeOfficial guidance and service information↗
- tax.gov.aepage updated 10 Sep 2026↗
- tax.gov.aepage updated 22 May 2024↗