A foreign bank wants proof that you are taxed in the UAE, or a client abroad asks for it before releasing a payment. The document they want is the UAE Tax Residency Certificate, which the Federal Tax Authority (FTA) issues.
The FTA issues it through its Tax Residency Certificates platform, which its service page describes as available "24 hours a day, 7 days a week". The FTA page, updated 11 August 2026, opens eligibility to "All persons that are UAE Tax Resident under UAE Tax Legislation, or UAE Tax Resident under the application of a Double Taxation Agreement". It lists a "(10) Ten business days" processing time from receipt of a completed application and fee lines from AED 50 upwards, by applicant type.
This article sets out the tests, documents, fees and period rules as published. For the wider tax picture, start with the overview of UAE corporate tax. This article does not interpret any double taxation agreement.
What the FTA issues, and what it is called
The FTA's service page is titled "Issuance Of Tax Certificates For Tax Residency". It describes three outputs:
- "Tax Residency Certificates to enable applicants, being a Tax Resident in the UAE, to take advantage of provisions under DTAs" (double taxation agreements).
- Tax Residency Certificates "for purposes other than the application of a DTA".
- An "International Form stamped by the FTA, to confirm the Tax Residency status".
The FTA's Taxpayer User Manual for the platform, dated 05 February 2025, names two request types: "TRC for Domestic Tax Purpose" and "TRC for Treaty Purpose". It names "Natural Person, Juridical and Juridical Government" applicants.
The name differs between official texts: "Tax Residency Certificate" (FTA) and "Tax Residence Certificate" (Cabinet Resolution No. (85) of 2022). Use the FTA's name when you apply.
The TRC platform's landing page describes the certificate only as enabling applicants "to benefit from Double Tax Avoidance Agreements (DTAA)", while the service page and manual also describe a non-treaty certificate. Ask your recipient which purpose it needs before you apply.
The platform also lists a Commercial Activities Certificate, issued "to enable applicants to refund VAT paid outside the UAE". The user manual states: "User will be eligible to apply for commercial activities certificate holding a valid VAT TRN." For that registration, see VAT registration in the UAE.
The legal tests, quoted
Cabinet Resolution No. (85) of 2022 Concerning Determining the Tax Residence is shown as "Active" on the UAE Legislation portal, effective 01 March 2023. Article 5(1) links the certificate to its tests: a person "considered as a Tax Resident in the State in accordance with the provisions of Articles (3) or (4) of this Resolution may submit an application to the FTA". Article 3 covers legal persons; Article 4 covers natural persons.
Companies and other legal persons (Article 3)
Article 3 treats a legal person as a tax resident in two cases, quoted as the portal returned them:
- "If it was established, formed, or recognised in accordance with the legislation in force in the State, not including the branch that is registered by a foreign legal person in the State."
- "If it is considered a Tax Resident under the applicable Tax Law in the State."
If your UAE presence is a branch, see branch, subsidiary or representative office in the UAE for the structures, and take the residency question to a licensed tax adviser.
Individuals (Article 4)
Article 4 sets three routes for a natural person:
- "If his usual or main place of residence and the centre of his financial and personal interests are in the State or if it fulfils the conditions and criteria specified by a decision issued by the Minister."
- "If he has been physically present in the State for a period of one hundred and eighty-three days (183) or more, during the relevant twelve (12) consecutive month period."
- Presence of "ninety (90) days or more, during the relevant twelve (12) consecutive months". The person must hold "the nationality of the State, a valid residence permit in the State or the nationality of any of the member" states of the Gulf Cooperation Council. They must also meet one of two conditions: "Having a permanent place of residence in the State." or "Practising a job or business in the State."
Read Article 4 in full on the UAE Legislation portal before relying on its wording.
Ministerial Decision No. 27 of 2023, in the FTA-hosted unofficial translation, adds detail for individuals. Article 3 on day counting begins: "All days or parts of a day on which a natural person is physically present in the State count towards the total number". Article 5 describes a permanent place of residence as "A furnished house, apartment, room or any other form of dwelling, made continuously available", which is "not required to be owned by the natural person but can be rented or otherwise occupied".
Certificates for treaty purposes
The FTA page states: "A Tax Residency Certificate for DTA purposes will be issued based on Ministerial Decision No. 247 of 2023 on the Issuance of Tax Residency Certificate for the Purposes of International Agreements." That decision refers to "a Person who meets the conditions of tax residency in the State pursuant to the relevant International Agreement". Whether a treaty's conditions are met is a question for a licensed tax adviser, not for this article.
For non-treaty certificates, the FTA's terms say both company and individual applicants "must meet the criteria set out in Cabinet Decision No. 85 of 2022 for the relevant 12-month period". For individuals, the terms add "read together with Ministerial Decision No. 27 of 2023".
Documents the FTA lists
The FTA service page lists documents for individuals in three cases, matching the route relied on.
| Case on the FTA page | Documents, quoted from the FTA service page |
|---|---|
| Case 1: 183 days or more | "Emirates ID or a passport with an entry and exit report from the Federal Authority of Identity and Citizenship or a local competent Government entity." |
| Case 2: 90 to 182 days | "Emirates ID and passport with an official entry/exit report, and proof of UAE employment/business or a permanent place of residence in the UAE." |
| Case 3: primary residence and centre of interests | "Emirates ID and passport with an official entry/exit report, proof of financial and personal interests in the UAE, proof of usual or primary residence in the UAE, and proof of source of income, if applicable." |
For companies and other juridical persons, the page lists:
- "Valid license and lease agreement"
- "Certificate of Incorporation"
- "UAE Corporate Tax TRN (if available)"
- "Memorandum of Association, Authorized signatory's Emirates ID and passport with proof of authorization, and proof of effective management and control in the UAE, where applicable."
The user manual also mentions "A bank statement issued by a local bank covering 6 months within the financial year", which is not in the service page's lists. Prepare from what the platform asks you to upload for your request type.
On foreign forms, the FTA page states: "The International Form must be properly completed (the FTA cannot complete it on your behalf) and duly signed (and stamped, in the case of a juridical person applicant) by the applicant before submission to the FTA."
Fees, as the FTA page shows them
The FTA page states that the fees are set by "Cabinet Decision No. 65 of 2020 on the Fees for the Services Provided by the Federal Tax Authority, and its amendments". It adds that they "shall not be refundable in case of rejection of the Application". The lines below are copied from the page.
| Fee label on the FTA page | Amount shown |
|---|---|
| "A submission fee for the service" | (50) AED |
| "Fees for each hard copy certificate requested" | (250) AED |
| Issuance of an electronic certificate to "a Registrant with the FTA (Tax Registrants with a Corporate Tax TRN)" | (500) AED |
| Issuance to "a natural person not registered with the FTA (Natural persons without a Corporate Tax TRN)" | (1,000) AED |
| Issuance to "a legal person not registered with the FTA (Juridical persons without a Corporate Tax TRN)" | (1,750) AED |
These are government charges. Third-party costs, such as translation or adviser fees, and any provider's service fee are separate. The page states: "Applicants will be required to settle the applicable fees for the service in full, before being able to complete the submission." The user manual adds that "the initial fee of AED 50 will not be refunded upon cancellation".
The AED 500 line is tied to a Corporate Tax TRN. If you hold a VAT TRN only, ask the FTA which line applies before you pay. For registration itself, see corporate tax registration in the UAE. We did not find any statement on VAT on these fees on the FTA service page reviewed on 20 September 2026.
Fees checked on 20 September 2026.
Which 12 months, and when you can apply
The FTA page sets an outer limit: "A Tax Residency Certificate cannot be issued to cover a future period (i.e., for a Tax Period or a 12-month period that has not commenced), or for a period exceeding 12 months." Check that the period your recipient needs has started.
FAQ 6 on the FTA page sets timing within a period by applicant type:
- "Juridical Person: you can apply after (3) three months into the period or any time after expiry of the period."
- "Natural Person: you can apply as soon as the criteria to be Tax Resident in the UAE are met."
- "Government Entities and Government Controlled Entities: You can apply from (1) one day into the period or anytime after expiry of the period."
Two statements on the same page for companies
The same FTA page also states, in its Terms and Conditions: "An applicant that is a juridical person and applying for a Tax Residency Certificate must be already incorporated or established for at least 12 months." Its FAQ 7 states: "A company must be established for 12 months before being eligible to apply for the Tax Residency Certificate." We have not reconciled these statements with FAQ 6. A company established less than 12 months ago can ask the FTA how they apply before paying the non-refundable fees.
Processing and delivery
The FTA page gives "(10) Ten business days from the date the completed application was received". For a hard copy: "(5) Five business days from the date the relevant fee payment is completed." It adds: "Delivery is only available to an address in the UAE." FAQ 5 states that after payment and approval "a digital Tax Residency Certificate will be sent to their registered email ID", and that it becomes downloadable from the platform on EmaraTax. These are published times, not a promise.
An older FTA page that differs
A second FTA page, "Issuance of Tax Residency Certificate", last updated 15 September 2022, was returned by a server-side reading on 20 September 2026, but the same address showed a page-not-found error in a normal browser that day. It may have been withdrawn. It states: "An Applicant who is a natural person must have been residing in the UAE for at least 180 days." Its fee wording is "AED 500 for all tax registrants." It also words the company rule, validity and processing time differently from the current page.
The current page and Cabinet Resolution No. (85) of 2022 use the 183-day and 90-day routes quoted above. If anyone quotes the 180-day figure, ask the FTA which applies.
The two-column checklist
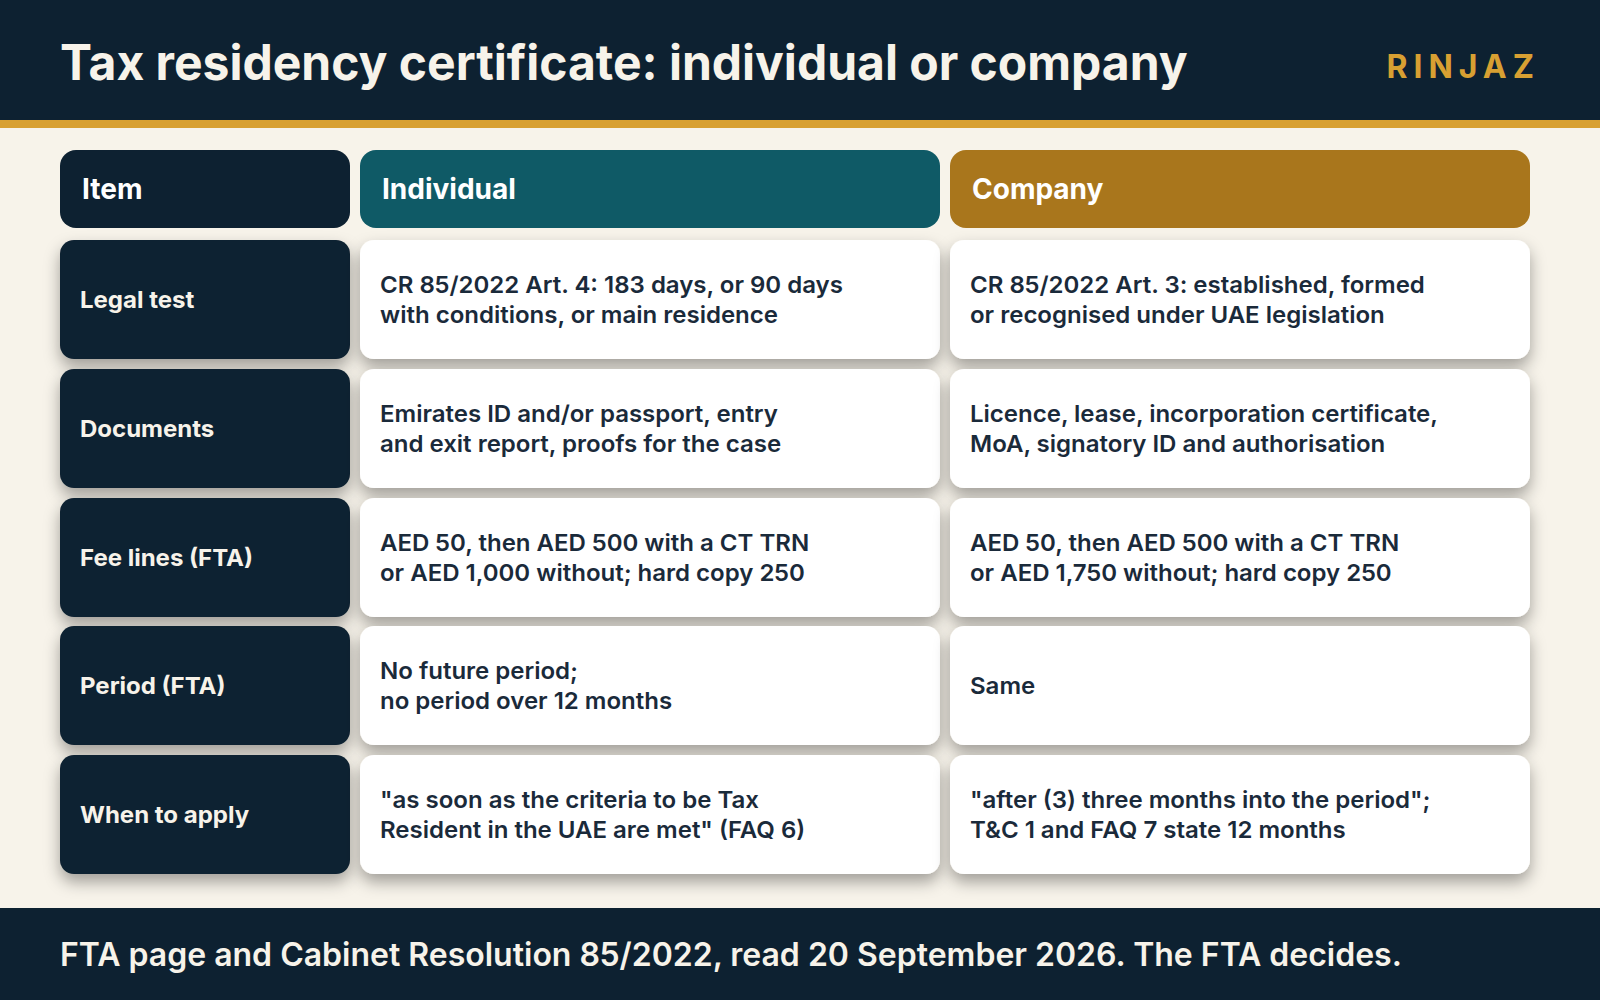
Practical asset: the tax residency certificate eligibility and evidence checklist. Fill in one column, date it and keep it with your application. It organises the published requirements; it does not decide eligibility. Sources are the FTA service page (FTA), Cabinet Resolution No. (85) of 2022 (CR 85/2022), Ministerial Decision No. 27 of 2023 (MD 27/2023) and Ministerial Decision No. 247 of 2023. | Item | Individual (natural person) | Company (juridical person) | |---|---|---| | Legal test (non-treaty) | CR 85/2022 Art. 4: main residence and centre of interests, or the conditions set by a Minister's decision; or 183 days or more; or 90 days or more with the nationality, residence permit or GCC condition plus a permanent place of residence or a job or business. Read with MD 27/2023. | CR 85/2022 Art. 3: "established, formed, or recognised" under UAE legislation, excluding "the branch that is registered by a foreign legal person"; or tax resident under the applicable Tax Law. | | Treaty purpose | Ministerial Decision No. 247 of 2023: "the relevant International Agreement". Ask a licensed tax adviser. | Same. | | Documents (FTA) | Case 1, 2 or 3 list, matching the route relied on: Emirates ID, passport or both as the case lists, an entry and exit report, and the proofs listed for the case. | Licence and lease, Certificate of Incorporation, Corporate Tax TRN "(if available)", MoA, signatory's ID with proof of authorisation, proof of management and control "where applicable". | | Fee line (FTA) | AED 50 submission, then AED 500 with a Corporate Tax TRN or AED 1,000 without one; AED 250 per hard copy. | AED 50 submission, then AED 500 with a Corporate Tax TRN or AED 1,750 without one; AED 250 per hard copy. | | Period (FTA) | No future period; no period over 12 months. | Same. | | When to apply (FTA FAQ 6) | "as soon as the criteria to be Tax Resident in the UAE are met" | "after (3) three months into the period", but see the 12-month statements in T&C 1 and FAQ 7. | Questions to settle before you apply 1. Which purpose does the recipient need: a treaty certificate, a non-treaty certificate or its own form stamped? [ ] 2. Which 12-month period does the recipient want covered, and has it started? [ ] 3. Which route or case do you rely on, and do your documents match that case? [ ] 4. Do you hold a Corporate Tax TRN, which decides the fee line on the FTA page? [ ] 5. Company only: has it existed for 12 months, and if not, what did the FTA say? [ ] 6. Do you need a hard copy, and is your delivery address in the UAE? [ ] 7. Is any foreign form completed and signed (and stamped, for a company) before upload? [ ] 8. Treaty questions: have you taken them to a licensed tax adviser? [ ]
Two worked examples:
An employee with a UAE residence permit is asked by a foreign pension fund for proof of residence for the last calendar year. The year has ended, so it is not a future period. She counts her days from an official entry and exit report and identifies which of the FTA's three cases fits. With no Corporate Tax TRN, the FTA page shows the AED 1,000 line and the AED 50 submission fee.
A mainland company incorporated eight months ago is asked by a foreign customer for a certificate. FAQ 6 refers to "three months into the period", while T&C 1 and FAQ 7 refer to 12 months of establishment. Before paying non-refundable fees, the finance manager puts the question to the FTA and records the reply. For the bank side, see opening a UAE company bank account.
After the certificate is issued
FAQ 9 on the FTA page explains verification: "Please visit the TRC verification page on Certificate Verification page. Alternatively, you can scan the barcode on the certificate to access the same page and verify the certificate." Tell your recipient about this route when you send the certificate.
If the recipient asks for attestation, ask exactly what they need. For how UAE documents are attested in general, see the UAE document attestation guide. For a treaty's text, the FTA page points to the Ministry of Finance: "The list of treaties, details and documents can be found on Ministry of Finance website on the following page: International Treaties Dashboard."
We did not find a validity period on the current FTA service page or the user manual reviewed on 20 September 2026; the page describes the period covered. If a recipient asks about validity, ask which period they need covered.
Who decides, what you prepare, what a provider can do
What the authority decides. The FTA decides each application. Article 5(3) of Cabinet Resolution No. (85) of 2022 states that if the FTA "is satisfied that the applicant meets the conditions", it "may approve the application and issue a Tax Residence Certificate". For treaty certificates, Ministerial Decision No. 247 of 2023 uses the same "may approve" wording. No provider decides residency.
What the individual or company prepares. The choice of purpose and period, the documents for the case relied on, any foreign form completed and signed, the fee payment, and a record of any question put to the FTA.
What a provider can do. Within its licensed activity, a provider can help collect documents, check them against the FTA's published lists and track the application. It cannot decide residency or interpret a treaty. The FTA page states that the International Form must be completed and signed "by the applicant".
RINJAZ is not a licensed tax adviser. This article describes published requirements. Obtain advice from a licensed UAE tax adviser before acting.
This article does not interpret any double taxation agreement.
Last verified: 20 September 2026. Information verified against official sources on 20 September 2026.
If you are preparing documents for a UAE Tax Residency Certificate application, contact RINJAZ to confirm availability, scope and quotation. RINJAZ is a privately licensed UAE service provider. It is not a government entity and does not act for any authority.
A provider's role, within whatever its licensed activity covers, is to prepare documents, submit them through the correct channel and track progress. The Federal Tax Authority decides whether a Tax Residency Certificate is issued, and no provider can promise the outcome.
Clear answers, without the clutter
How much does a UAE Tax Residency Certificate cost?
Can a company less than 12 months old apply?
Can I get a certificate for the current year before it ends?
What is the 90-day route for individuals?
How long does the FTA take to issue the certificate?
How can a foreign bank check that my certificate is genuine?
Official sources
Primary government and institutional references used to verify this guide. Open any source in a new tab for the current authority wording.
- tax.gov.aepage updated 11 Aug 2026↗
- tax.gov.aepage updated 15 Sep 2022↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- tax.gov.aeOfficial guidance and service information↗
- mof.gov.aeOfficial guidance and service information↗
- tax.gov.aeOfficial guidance and service information↗
- trc.tax.gov.aeOfficial guidance and service information↗
- mof.gov.aepage updated 17 Sep 2026↗