Your licence renewal stalls because the licensing authority wants beneficial owner details. Or a new shareholder has bought in and nobody knows what must be filed. Or an auditor asks about a 2021 economic substance notification. Each of them starts from an event in the company's life, so keep your own dates.
The short answer, as published on 20 September 2026: Cabinet Resolution No. (109) of 2023 requires a company to keep a Real Beneficiary Register, submit it to its Registrar within 60 days, and report changes within 15 days. On economic substance, the Ministry of Finance announced on 14 October 2024 "the cancellation of economic substance reporting requirements for companies for financial years ending after 31 December 2022". Earlier years, and any penalties the Federal Tax Authority (FTA) imposed, remain the company's responsibility.
For the tax side, start with the overview of UAE corporate tax. This article covers beneficial ownership and economic substance only.
The two regimes, as read on 20 September 2026
| Instrument | Status on the UAE Legislation portal | What it governs |
|---|---|---|
| Cabinet Resolution No. (109) of 2023 | Issued 06 Nov 2023; Effective 16 Nov 2023; "Active" | Real Beneficiary Register, filing with the Registrar, updates |
| Cabinet Resolution No. (132) of 2023 | Issued 15 Dec 2023; Effective 30 Dec 2023; "Active" | Administrative penalties for breaches of Resolution 109 |
| Cabinet Resolution No. (57) of 2020 | Issued 10 Aug 2020; "Active"; last updated 02 Sep 2024 | Economic substance, now limited to fiscal years up to 31/12/2022 |
Article 22 of Resolution 109 states: "The Cabinet Resolution No. (58) of 2020 regulating Real Beneficiary Procedures shall be cancelled." If a guide or a form in front of you cites Resolution 58 of 2020, check it against the current text.
One effective date differs between official sources. The UAE Legislation portal shows Resolution 109 effective on 16 Nov 2023. The Jebel Ali Free Zone (Jafza) guide on beneficial owners states that it "came into effect on 15 December 2023", and the same guide opens by describing Resolution 58 of 2020. A Jafza company should ask Jafza which text and date it applies.
Who counts as a real beneficiary
Article 5(1) of Resolution 109 sets the ownership test: "Real Beneficiary of Legal Person is whoever owns or finally controls Legal Person, through direct or indirect ownership shares of (25) twenty-five per cent or more of Legal Person capital."
Article 5(3) adds: "Real Beneficiary shall be tracked through any number of Legal Persons or arrangements of any kind." If a foreign parent owns your UAE company, read Article 5(3) with an adviser. For the corporate forms involved, see branches, subsidiaries and representative offices in the UAE.
We quote paragraphs (1) and (3) of Article 5 only; read the full article with an adviser.
Who is outside Resolution 109
Article 3(1) states that the Resolution applies to "Registrar and Legal Persons licensed or registered in the State." Article 3(2) then excludes three groups:
- "Companies wholly owned by the Federal or Local Government, or any other companies wholly owned by those companies."
- "Financial Free Zones"
- "Government Partner"
ADGM publishes its own regime, the "Beneficial Ownership and Control Regulations 2022". Other financial free zones were not reviewed; check your own zone's rules.
The register the company keeps
Article 8(1) requires the company to "maintain the details of the information of each Real Beneficiary in Real Beneficiary Register that it creates within (60) sixty days". The 60 days run "from the date of the implementation of this Resolution or from the date of the existence of this Legal Person."
Article 8(2) lists what the register holds for each real beneficiary:
- "Full name, nationality, date and place of birth."
- "Residence or the address to which notices are sent under this Resolution."
- "Passport or the ID number, the State, and the issue and expiry dates."
- "Grounds on which he has become Real Beneficiary of Legal Person, and the date on which he has that capacity."
- "Date on which the person ceased to be Real Beneficiary of Legal Person."
Article 10 also requires a Partners or Shareholders Register; read its contents in the official text.
Three further rules in Article 11 shape the file:
- Article 11(4): the company must give the Registrar "the name of Natural Person residing in the State authorised to disclose to Registrar all data and information required by the law".
- Article 11(5): "No Legal Person, licensed or registered in the State, may issue Bearer Stocks."
- Article 11(6): shares issued "in the name of persons or Board Members" must be disclosed to the Registrar "within (15) fifteen days".
Article 15(1) requires the register data to be "accurate and updated."
Deadlines that start with an event, not a date
We did not find one annual filing day in Resolution 109 as read on 20 September 2026. Each clock starts when something happens: the company's existence (60 days to create the register, Art. 8(1)), licensing and registration (60 days to submit both registers, Art. 11(1)), a Registrar's request (14 days, Art. 11(2)), and any change to the data (15 days, Art. 15(2)). Part A of the calendar below lists each one with its article.
Article 11(3) ties submission to "incorporation, licensing, registration, renewal, modification or other cases that Registrar may deem necessary for this." We did not find a separate annual refiling requirement in the text of Resolution 109 as read on 20 September 2026. Ask your Registrar what it expects at each renewal.
If the company is changing its activities or partners, see adding or changing activities on a Dubai trade licence and plan the beneficial owner update alongside it.
A worked example: questions after a share transfer
A mainland company has two shareholders, each at 50 per cent. One sells 30 per cent of the capital to a new investor. These are questions for the Registrar or a licensed adviser, not conclusions.
- The new investor now holds 30 per cent. Article 5(1) uses a threshold of "(25) twenty-five per cent or more". Ask an adviser whether the investor is a real beneficiary and whether a new register entry with the Article 8(2) details is needed.
- The seller's holding falls to 20 per cent. Article 8(2)(e) provides for the "Date on which the person ceased to be Real Beneficiary". Article 5(1) also refers to control and to indirect ownership, so ask an adviser whether this entry applies.
- Article 15(2) requires "any amendment or change to the data or information under this resolution" to go to the Registrar "within (15) fifteen days from the date of the amendment or change." Ask your Registrar whether the transfer is such a change and which date starts the period. The penalty table attached to Resolution 132 describes one violation as failing "to update the Partners or Shareholders Register within (15) fifteen days from the date of the change or becoming aware of it."
Keep dated records of the transfer, any register update and any submission.
Where the filing goes: your Registrar
Article 1 defines the Registrar as "The Competent Authority supervising the Register of commercial names of different establishments registered in the State." A Ministry of Economy and Tourism (MoET) article of 26 September 2022 referred to "39 registrars from all economic development departments and free zones in the country."
We did not find a single federal UBO filing portal, or a MoET filing channel, on the MoET articles of 21 December 2023 and 26 September 2022 or the u.ae National Economic Register page, reviewed on 20 September 2026.
Each authority reviewed publishes its own channel or rule:
| Registrar | What its page states | Page read |
|---|---|---|
| Dubai Department of Economy and Tourism (DET) | Related service listed as "Add/Modify Beneficial Owner - DET" | dubai.ae, last modified 03-04-2026 |
| DMCC | "Go to 'Company Service', under 'Ultimate Beneficial Owner' click on 'Declare /Update Ultimate Beneficial Owner'." | UBO Declaration Guideline, Version 3, 11 January 2024 |
| Jafza | "All existing companies registered in Jafza (Onshore & Offshore) must also complete the UBO KYC form and submit it through Dubai Trade." | Jafza guide dated June 01, 2022 |
| ADGM | "Report changes to the Registrar within 15 days of a change." | ADGM Beneficial Ownership and Control page |
We did not find the steps, fee or processing time of the DET service on the dubai.ae page read on 20 September 2026; ask DET directly. Other licensing authorities were not reviewed.
Before you file, confirm the licence details the Registrar holds. See how to verify a UAE trade licence.
When a free zone page and the resolution differ
DMCC's guideline states that "In case any such information changes should promptly notify DMCC". It gives no day count. Resolution 109, Article 15(2), sets "(15) fifteen days". DMCC also grounds its declaration on "the UAE Federal Antimoney laundering (AML) Law and the Anti-money laundering (AML) By-laws", not on Resolution 109. A DMCC company should ask DMCC which deadline it applies. Anti-money laundering duties themselves are covered in goAML registration and AML obligations in the UAE.
Penalties: what has been confirmed
Resolution 109, Article 18, states that "Registrar may impose one or more penalties from the list of administrative penalties issued by resolution of the Cabinet". That list is the table attached to Cabinet Resolution No. (132) of 2023.
The table's columns, confirmed in a browser reading of the portal PDF on 20 September 2026, run "First Time", "Second Time", "Third Time". Row 1 reads:
| Violation (row 1) | First Time | Second Time | Third Time |
|---|---|---|---|
| "The Legal Person fails to correctly Register the Real Beneficiary details of the Real Beneficiary." Legal Ref. "Article (6) and (7)" | "A Written Notice to the Legal Person to comply within (15) fifteen days from the date of the Notice." | "(20,000) twenty thousand AED and a Notice to the Legal Person to correct the Violation within (15) fifteen days" | "(40,000) forty thousand AED, along with notifying the Legal Person to correct the Violation." |
The browser reading covered row 1 only, so we do not state amounts for the other rows. Read the full table on the portal or ask your Registrar.
Article 3(2) of Resolution 132 adds a further step. "In addition to the penalty of the fine imposed on Violations committed for the third time", the Registrar "has the right to suspend the commercial licence and close the commercial store of the Violating Legal Person". The suspension "is removed after he pays the Violation fine and corrects it". Article 4 states that the Cabinet "has the power to make any amendments to the fees mentioned herein". Check the portal for amendments before relying on these amounts.
Economic substance: what the Ministry of Finance says now
The Ministry of Finance (MoF) announced on 14 October 2024 "the cancellation of economic substance reporting requirements for companies for financial years ending after 31 December 2022". It linked this to "Cabinet Decision No. (98) of 2024, which amends certain provisions of Cabinet Decision No. (57) of 2020". MoF added: "This amendment aligns with the implementation of the UAE's federal corporate tax system on business and corporate profits." For corporate tax registration, see corporate tax registration in the UAE.
The consolidated text of Resolution 57 of 2020 on the UAE Legislation portal carries Article 2 BIS: "The provisions of this Resolution shall apply to fiscal years commencing from 01/01/2019 up to and including the fiscal year ending on 31/12/2022."
Note the wording. MoF refers to financial years "ending after" 31 December 2022, not years starting after it. If your financial year ran across that date, confirm its position with MoF or the FTA rather than assuming.
We did not find the text of Cabinet Resolution No. 98 of 2024 on the pages reviewed on 20 September 2026.
Earlier years have not gone away
The same MoF announcement states that companies "remain responsible for fulfilling compliance obligations for prior years". That includes "adhering to information or amendment requests from regulatory authorities or the Federal Tax Authority, and paying any penalties imposed by the Federal Tax Authority."
The FTA's ESR page, updated May 22, 2024, states that under Resolution 57 of 2020 the FTA "is hereby appointed as the National Assessing Authority". Its listed functions include "Impose the administrative penalties pursuant to Articles 13, 14 and 15" and "Head and decide on appeals pursuant to Article 17". The page gives the contact FTAESR@tax.gov.ae.
The consolidated text of Resolution 57 of 2020 on the UAE Legislation portal includes, among others, these fines:
- Article 13(1): "An administrative fine of twenty thousand Dirham (AED 20.000)" for a licensee that "fails to submit the notice".
- Article 14(1): "An administrative fine of fifty thousand Dirham (AED 50.000)" for "Failure to submit the real economic activities report" or "Failure to fulfil the requirements of real economic activities for any fiscal year."
We did not find an official statement that ESR penalties were waived or refunded on the MoF announcement, the MoF ESR page, the FTA ESR page or the FTA administrative penalty waiver service page, reviewed on 20 September 2026. The waiver page cites Cabinet Decision No. 105 of 2021 and does not mention ESR. If your company has an open ESR penalty, contact the FTA.
Official pages that still describe annual filing
MoF's ESR page, last updated 17/09/2026, states that in-scope entities must submit "within 12 months from the end of their financial year: An annual notification form; An Economic Substance Report". The u.ae ESR page, updated 22 May 2025, does not mention Cabinet Decision 98 of 2024. Ask MoF or the FTA which applies to your years.
Who decides, who prepares, what a provider can do
The authority decides. Your Registrar decides whether beneficial owner data is complete, what it asks for and whether a penalty applies. For earlier ESR years, the FTA imposes penalties and decides appeals. No provider decides any of these.
The company prepares. It identifies its real beneficiaries, keeps both registers accurate, names a resident authorised person, files within the event deadlines and keeps dated evidence. For ESR, it keeps its filings for years up to 31 December 2022 and any FTA correspondence.
A provider can assist, conditionally. Within its licensed activity, a provider can help assemble documents and track replies. Who is a real beneficiary is a question for a licensed adviser.
The compliance calendar
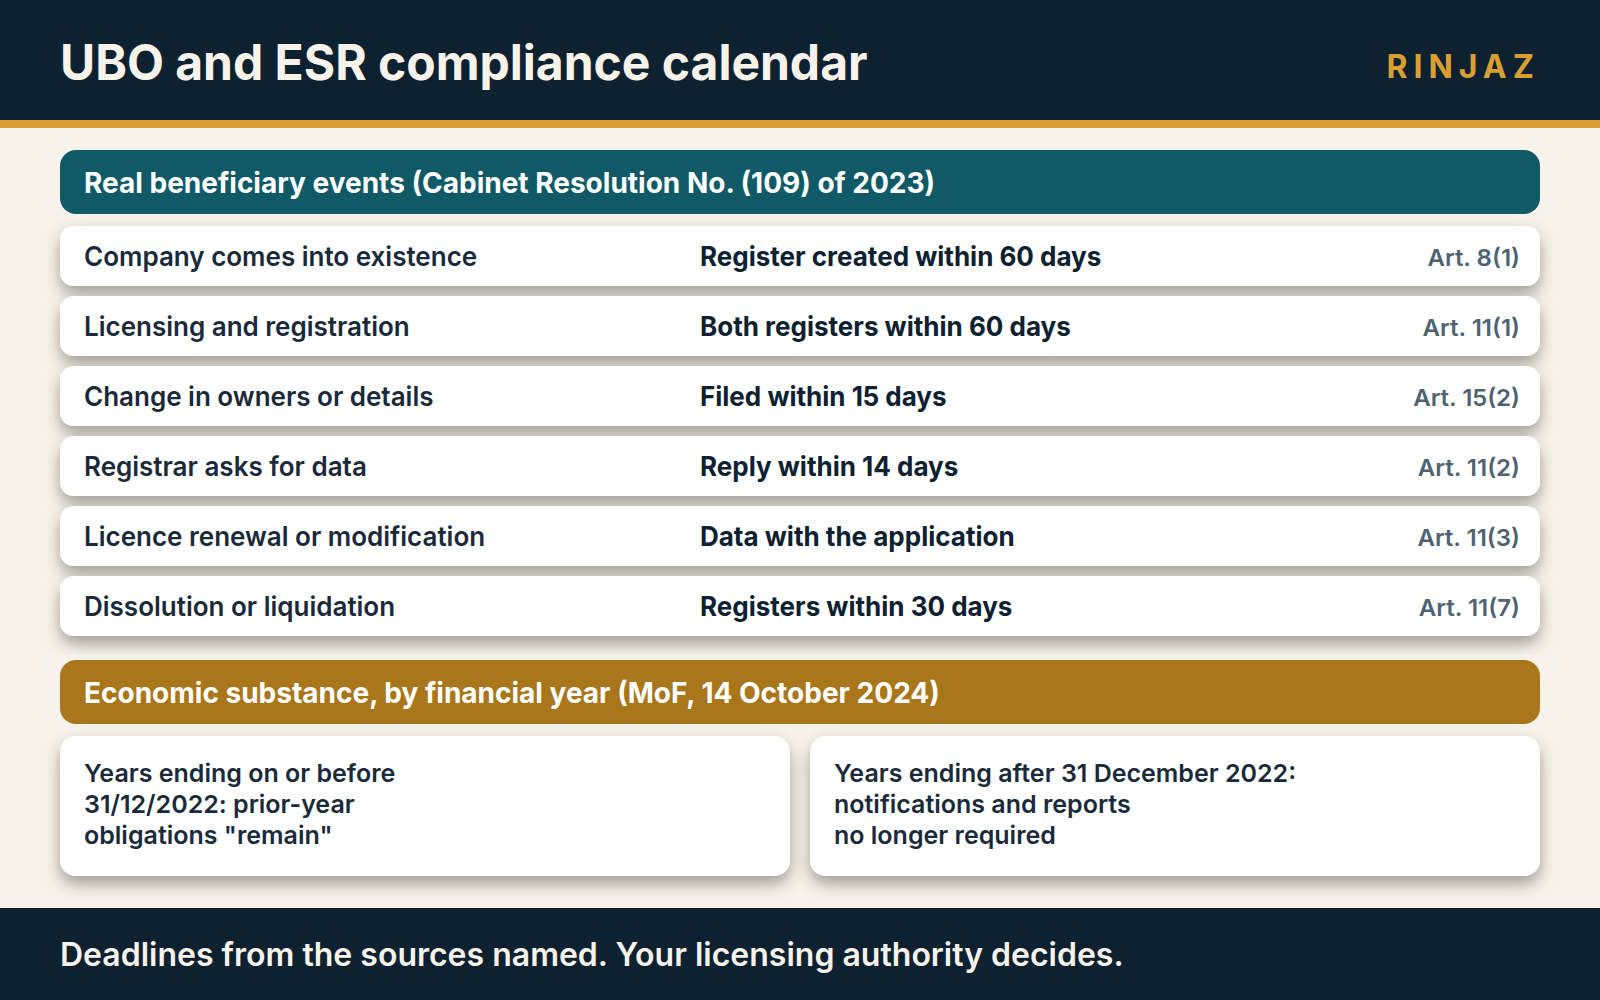
Practical asset: the real beneficiary and ESR compliance calendar. Fill in the dates for your company, keep the sheet with the registers and take Part C to your licensing authority. It records deadlines from the sources named; it does not decide your position. Part A. Real beneficiary events (Cabinet Resolution No. (109) of 2023) | Event | Date it happened | Deadline | Due by | Done | |---|---|---|---|---| | Company came into existence | ____ | Register created within 60 days (Art. 8(1)) | ____ | [ ] | | Licensing and registration | ____ | Both registers submitted within 60 days (Art. 11(1)) | ____ | [ ] | | Change in owners, shares or beneficiary details | ____ | Change filed within 15 days (Art. 15(2)) | ____ | [ ] | | Shares issued in the name of persons or board members | ____ | Disclosed within 15 days (Art. 11(6)) | ____ | [ ] | | Registrar's request received | ____ | Reply within 14 days (Art. 11(2)) | ____ | [ ] | | Licence renewal or modification | ____ | Data submitted with the application (Art. 11(3)) | ____ | [ ] | | Dissolution or liquidation | ____ | Registers to the Registrar within 30 days (Art. 11(7)) | ____ | [ ] | Part B. Economic substance position by financial year (MoF, 14 October 2024; Resolution 57 of 2020, Art. 2 BIS) | Financial year | Position as published | Action | |---|---|---| | Years from 01/01/2019 ending on or before 31/12/2022 | Within Resolution 57 of 2020; prior-year obligations "remain" (MoF) | Check each year's notification and report were filed; keep FTA correspondence | | Years ending after 31 December 2022 | Notifications and reports no longer required (MoF) | Keep the MoF announcement on file | | A year that began before and ended after 31 December 2022 | MoF's wording refers to years "ending after 31 December 2022"; neither page names this case separately | Confirm with MoF or the FTA | Part C. Questions for your licensing authority 1. Which channel do you use for beneficial owner filings, and what documents does it ask for? 2. Which deadline do you apply to changes: the 15 days in Resolution 109, Article 15(2), or your own wording? 3. Who must be named as the resident authorised person under Article 11(4)? 4. Do you expect beneficial owner data again at each licence renewal under Article 11(3)? 5. Which effective date and which resolution does your guidance cite? 6. How will a submission be acknowledged, so we can evidence the date?
Closing the company: the registers outlive it
Article 11(7) states that "the liquidator shall hand over Real Beneficiary Register, the Partners or Shareholders Register, if any, or exact copy thereof to Registrar within (30) days". Article 11(8) requires the liquidator to keep the records "for a period of at least five (5) years from the date of its dissolution or liquidation."
For the wider process, see company cancellation and liquidation in the UAE.
RINJAZ is not a licensed tax adviser. This article describes published requirements. Obtain advice from a licensed UAE tax adviser before acting. This article describes published requirements and is not legal advice.
Fees checked on 20 September 2026.
Last verified: 20 September 2026. Information verified against official sources on 20 September 2026.
If you are preparing beneficial owner filings or gathering records for earlier economic substance years, contact RINJAZ to confirm availability, scope and quotation. RINJAZ is a privately licensed UAE service provider. It is not a government entity and does not act for any authority.
A provider's role, within whatever its licensed activity covers, is to prepare documents, submit them through the correct channel and track progress. Your Registrar decides on beneficial owner filings and the Federal Tax Authority decides on economic substance penalties, and no provider can promise the outcome.
Clear answers, without the clutter
Do I have to file my UBO declaration again each year?
How long does a company have to report a change of shareholder or beneficial owner?
What is the first penalty for registering real beneficiary details incorrectly?
Does my company still need to file an economic substance notification?
Who handles economic substance penalties and appeals for earlier years?
Does Cabinet Resolution No. (109) of 2023 apply to ADGM companies?
Official sources
Primary government and institutional references used to verify this guide. Open any source in a new tab for the current authority wording.
- uaelegislation.gov.aepage updated 06 Nov 2023↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aepage updated 15 Dec 2023↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- moet.gov.aeOfficial guidance and service information↗
- moet.gov.aeOfficial guidance and service information↗
- UAE Government Portalpage updated 17 Apr 2026↗
- dubai.aepage updated 03 Apr 2026↗
- dmcc.aepage updated 11 Jan 2024↗
- jafza.aeOfficial guidance and service information↗
- adgm.compage updated 14 Aug 2024↗
- mof.gov.aeOfficial guidance and service information↗
- uaelegislation.gov.aepage updated 02 Sep 2024↗
- uaelegislation.gov.aeOfficial guidance and service information↗
- mof.gov.aepage updated 17 Sep 2026↗
- tax.gov.aepage updated 22 May 2024↗
- UAE Government Portalpage updated 22 May 2025↗
- tax.gov.aepage updated 18 Sep 2026↗